Traditional solar and wind forecasts rely on the assumption that metered generation matches what an asset could have produced. That assumption is starting to break down as renewable assets increasingly provide not just energy, but also grid regulation services. Recent developments in Spain highlight what is to come in other renewables-heavy markets.
Recent developments in Spain highlight what is to come in other renewables-heavy markets.
Two kinds of regulation services matter here:
- Automatic Frequency Restoration Reserve (aFRR or secondary regulation) response begins within seconds of the TSO signal, reaches full activation within 5 minutes, and must be sustained for at least 15 minutes.
- Manual Frequency Restoration Reserve (mFRR or tertiary regulation) moves slower and can last longer. Full activation takes up to 15 minutes, the response holds for up to two hours, and a human dispatcher activates it rather than a control system.
Both aFRR and mFRR allow assets to provide frequency regulation UP or DOWN. This post concerns regulation DOWN, which is the most prevalent service provided by wind and solar assets.
Why Spanish solar and wind assets are leaning into grid regulation services
aFRR and mFRR regulation down services allow solar and wind assets to obtain additional revenues. Downward regulation gives an asset two revenue lines: a capacity payment for holding an aFRR band ready, and a separate settlement on the energy it holds back when the band is called.
This can substitute or complement the revenue they can obtain in the wholesale market. This is especially relevant for solar. Analysts estimate capture factors have fallen below 0.30 in high-irradiance months, and in some places, forward capture prices are sitting between €16 and €18/MWh through 2027.
The problem: regulation activity looks like normal curtailment to most models
Here's where the opportunity runs into a forecasting problem most IPPs haven't fully reckoned with. When a solar or wind asset gets called for aFRR or mFRR DOWN, its metered output stops reflecting what the sun or wind actually made available.
When a solar or wind asset gets called for aFRR or mFRR DOWN, its metered output stops reflecting what the sun or wind actually made available.
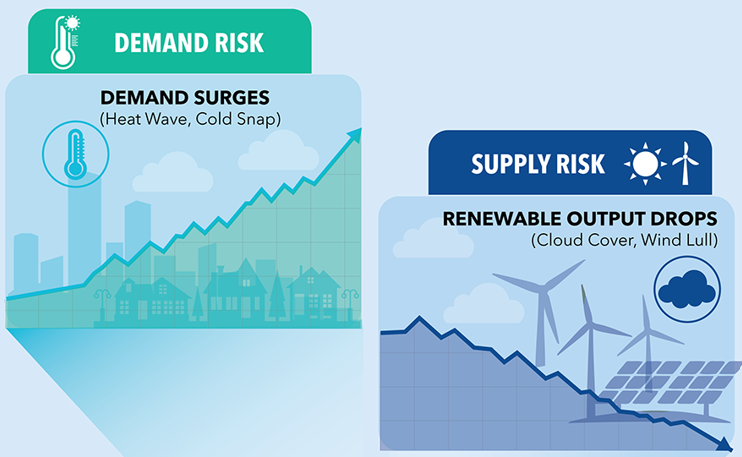
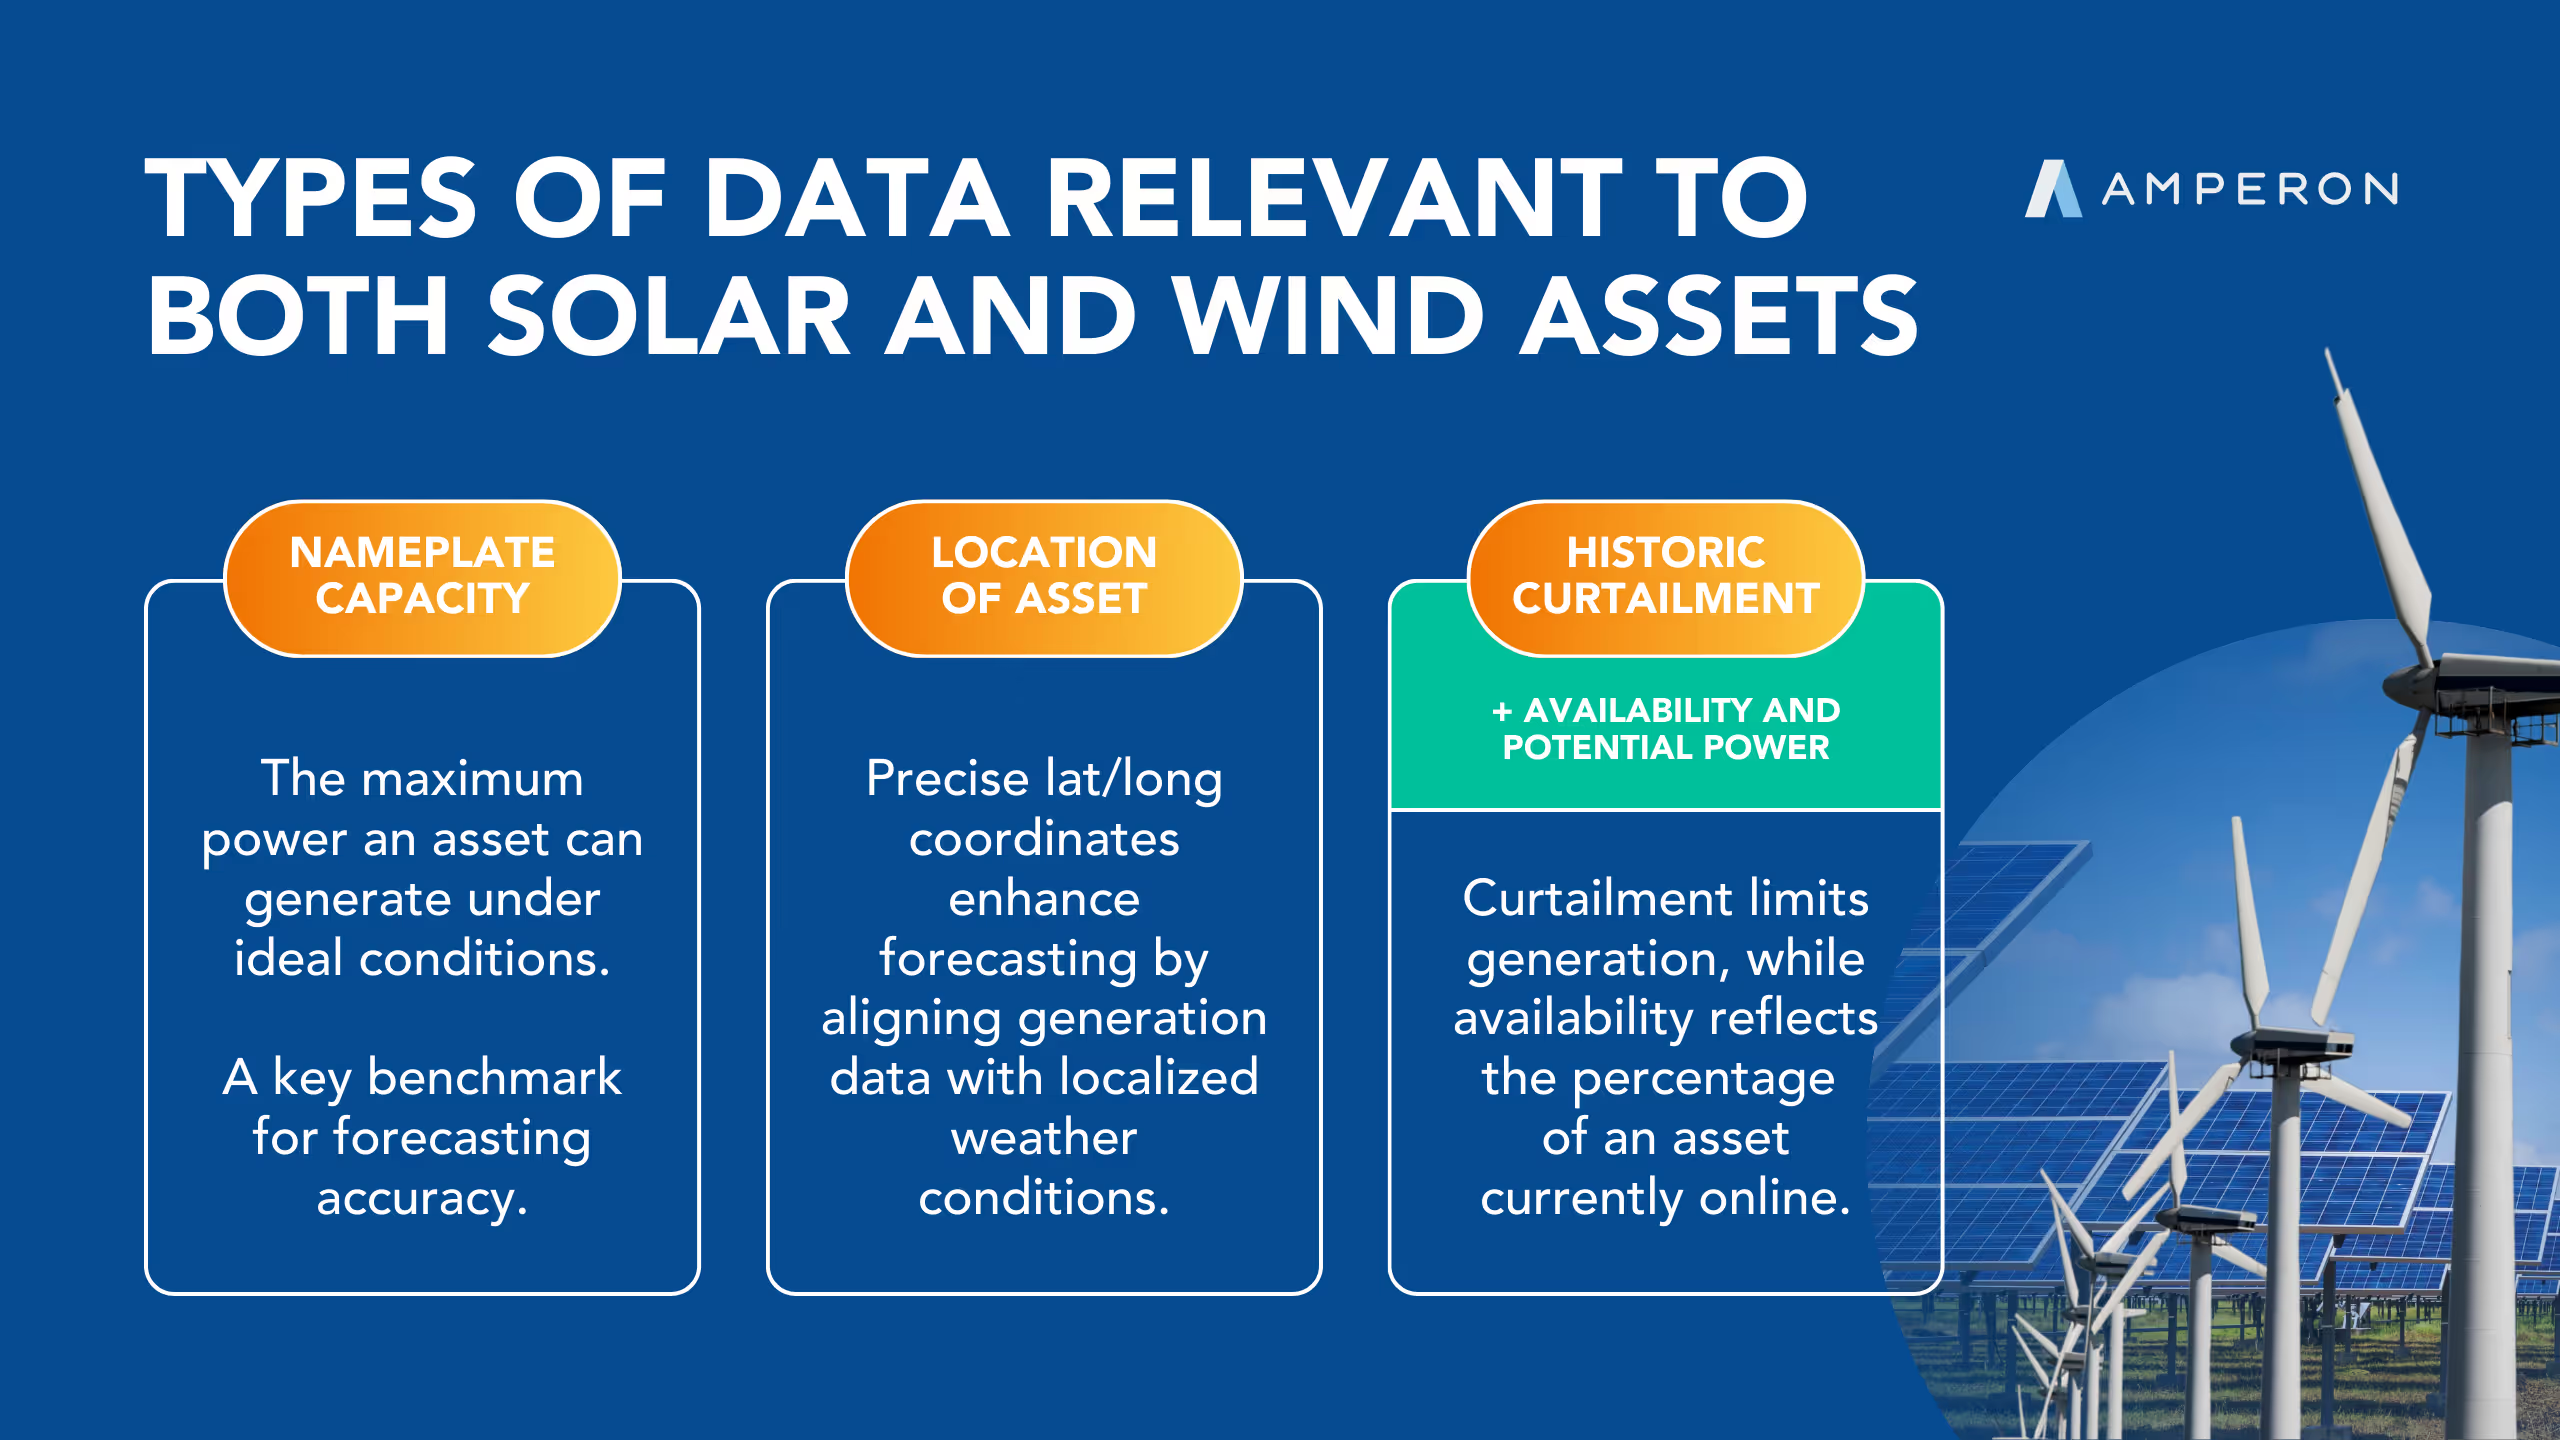
An asset capable of producing 100 MW might hold at 80 MW for fifteen minutes, and the meter simply records 80. Nothing in that number distinguishes a deliberate instruction from a cloud passing overhead or a mechanical fault.
Traditional forecasting models can't tell the difference either. They ingest historical actuals, and once a meaningful share of those actuals reflects regulation activity instead of true generation potential, the model treats curtailed behavior as normal.
The forecast doesn't fail all at once. It degrades gradually, under-forecasting potential output during exactly the hours an operator needs an accurate read to bid intelligently into both energy and ancillary services markets.
The problem also compounds as participation grows. An asset regulating 5% of hours sees a minor accuracy hit. One regulating 30% or more risks a forecast that's fundamentally unreliable.
How Amperon adjusts forecasts for curtailed assets
Amperon starts from a different assumption: metered actuals aren't automatically considered ground truth, and a model needs to know which periods to trust before it learns from them.
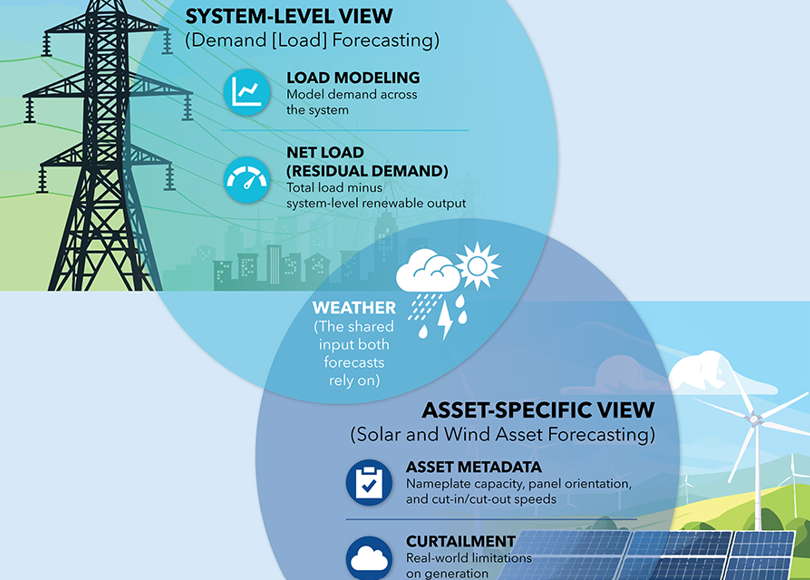
Our pipeline compares generation against expected output from weather and other factors and then classifies every period as uncurtailed, curtailed, scaled, or bad, adjusting model training accordingly. None of this requires a solar asset operator to send us a signal when regulation activity occurred. The detection runs directly off the generation data itself.
None of this requires a solar asset operator to send us a signal when regulation activity occurred.
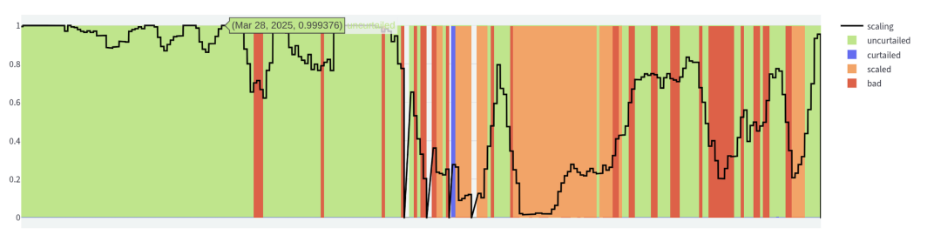
Once the affected periods are identified and set aside, the model forecasts potential power, meaning what the asset would have produced without the intervention, and gives the operator a number they can actually bid against.
Forecasting for IPPs participating in or considering ancillary services
Forecasting risk isn't a reason to stay out of aFRR and mFRR markets. It's a reason to be selective about who forecasts the asset.
Forecasting risk isn't a reason to stay out of aFRR and mFRR markets. It's a reason to be selective about who forecasts the asset.
An IPP that treats regulation services as a deliberate revenue strategy, rather than an occasional curtailment event to absorb, needs a forecasting partner that already accounts for it, not one that will need retraining and recalibration after the fact.
Spain's shift toward higher renewable penetration and tighter balancing requirements isn't slowing down. The operators best positioned to benefit are the ones who can participate in ancillary markets with confidence, knowing their forecast still reflects reality underneath the regulation activity.
Explore Asset Optimization Solutions